Shield AI has agreed to acquire Echodyne in a transaction valued at $5.3 billion, bringing a radar supplier into the defense technology company’s portfolio of autonomy software and aircraft. The companies say Echodyne radars are integrated into hundreds of counter-drone and security systems across more than 40 countries. Closing is expected in early 2027 and remains subject to regulatory approval.
Why combine radar and autonomy?
A radar can extend a system’s ability to detect and track objects, while autonomy software can help interpret observations and support mission planning. Bringing those technologies under one company could create opportunities to coordinate sensing and control across air and counter-drone systems. That is a strategic rationale, not proof that the combined products are already integrated or that customers will receive a new capability at closing.
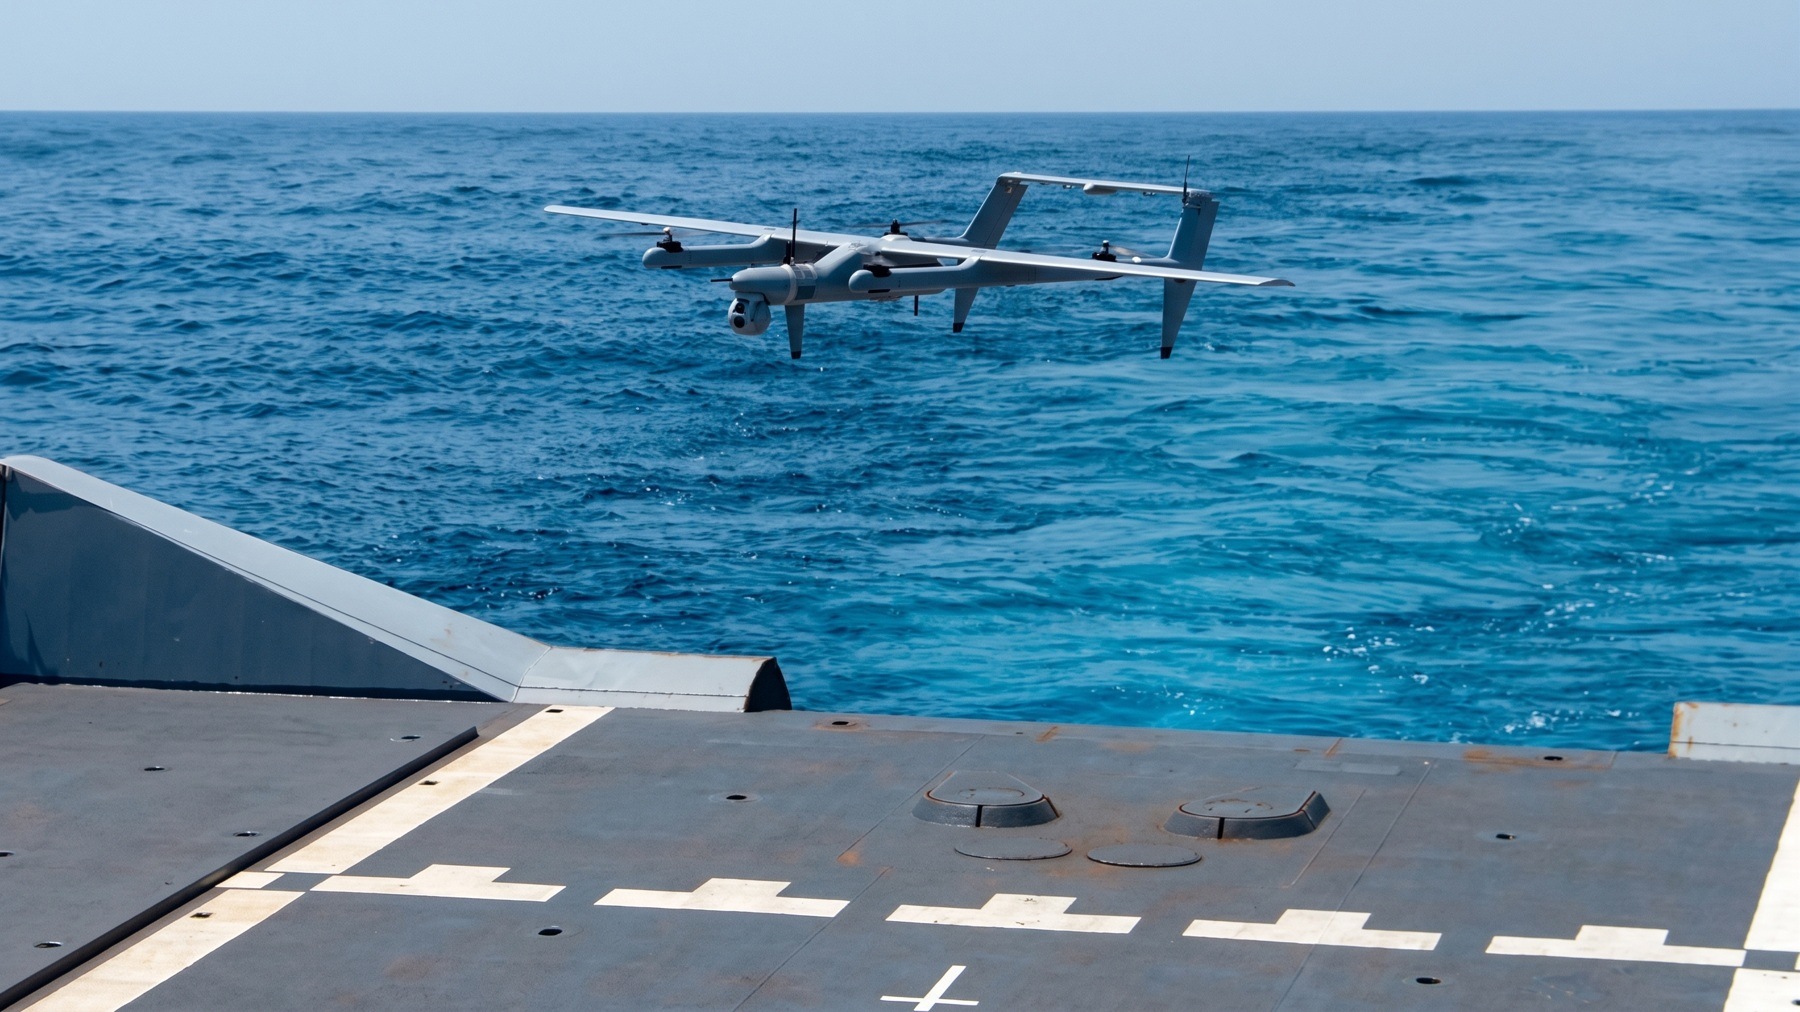
The announcement identifies Echodyne’s radar as part of counter-drone and security systems, while Shield AI’s portfolio includes Hivemind autonomy software, V-BAT and X-BAT aircraft, and simulation technologies. Those are complementary layers, but the release does not describe a combined system architecture, a product roadmap, or a customer deployment schedule. Integration across sensing, software and platforms will have to be demonstrated in specific configurations.
Financing and transaction conditions
Shield says it is raising $2.5 billion to support the transaction: $1 billion in Series H equity at a $28.8 billion post-money valuation, $1 billion in structured equity from funds managed by Blackstone, and $500 million in debt led by JPMorgan Chase. The company says $4.8 billion of the transaction value will be paid or issued at closing, with up to another $500 million contingent on Echodyne meeting agreed performance targets.
The financing structure and contingent portion matter to how the headline value should be read. The $5.3 billion figure is the stated transaction value, not a cash payment already completed. The proposed closing is months away, and approval conditions remain. The companies also cite expected triple-digit revenue growth this fiscal year, but the announcement does not supply a combined forecast or a post-acquisition operating plan.
What to watch
The near-term milestones are regulatory clearance and completion of the financing. After closing, useful evidence would include a published integration plan, named customer configurations, and tests showing what radar data changes in the autonomy system’s decisions. Until then, this is a significant portfolio and capital transaction rather than a demonstrated counter-drone performance upgrade.
For defense buyers, the acquisition may eventually affect supplier relationships, interfaces and support arrangements. Procurement teams should distinguish a common corporate owner from technical integration: interoperability still depends on documented interfaces, tested behavior, cybersecurity controls and sustainment responsibilities.
What the announced scale does and does not show
The reported footprint—hundreds of systems in more than 40 countries—helps explain why a radar business could matter to a company pursuing autonomy across multiple platforms. It is a company-reported installed-base description. The announcement does not break that figure down by customer, radar model, operating environment or level of system integration, so it should not be read as a measure of performance in any particular mission.
Radar and autonomy can complement one another, but their practical value depends on the details at the boundary between them. A buyer would need to know what tracks and confidence information are passed, how latency and uncertainty are represented, how software handles clutter or interrupted sensing, and what happens when sensor data conflicts with other inputs. None of those engineering questions is answered simply by placing the businesses under common ownership.
There is also a product and governance question. Customers may have fielded configurations that were selected, tested and supported under existing arrangements. A change in ownership can create an opportunity to coordinate product plans, while also raising questions about delivery schedules, technical support, upgrade paths and continued access to interfaces. The public announcement does not describe changes to current customer commitments or a transition plan.
Capital structure deserves separate scrutiny
The financing announcement is substantial, but its components should be considered separately from the strategic case. The stated $1 billion Series H equity round carries a $28.8 billion post-money valuation. Another $1 billion is described as structured equity managed by Blackstone, and the remaining $500 million as debt led by JPMorgan Chase. The release does not provide all terms needed to compare the economics of those instruments or to assess the combined company’s future capital needs.
The contingent portion of the purchase price also makes the headline value conditional in part. Up to $500 million depends on performance targets, according to the company. The release does not specify those targets in detail. Completion of the financing, regulatory review, and closing are separate milestones; none should be inferred from the announcement of an agreement.
Evidence to look for after closing
A credible integration case will become clearer through concrete disclosures: product roadmaps that identify interfaces, tests in representative operating conditions, independent or customer-validated results, and support commitments for existing deployments. It will also matter whether teams publish how the system behaves when radar observations are incomplete, ambiguous or unavailable. Those details would allow customers to evaluate safety, reliability and operator workload rather than relying on a portfolio-level claim.
Until those milestones appear, the strongest conclusion is bounded. Shield AI has announced an agreement to acquire a radar supplier with a reported international deployment base and has described a financing package for the transaction. The deal could give it more direct control over a sensing layer relevant to counter-drone and security systems. The actual technical gains, if any, remain to be demonstrated after approval, financing and integration.
Shield AI’s transaction announcement.
What would change the assessment
After approval and closing, look for disclosed interfaces, representative counter-UAS trials, independently checked results and support commitments for existing customers.
The wider impact
The transaction is a strategic move with a substantial financing package, but it is not yet evidence of integrated performance. The deal remains subject to review and is expected to close in early 2027, according to Shield AI.
For customers, the meaningful test will be whether the combined business can show measurable improvements while preserving reliable support for systems already in use. Until then, the acquisition establishes intent and ownership structure; technical outcomes remain ahead.
This analysis draws on the public sources linked in the text. Send corrections to [email protected].